AI-D&O
Management & board oversight
AI Directors and Officers Liability
Illustrative allegation
Shareholders allege that directors overstated the company’s AI capabilities or failed to oversee its use of AI.
Explore AI-D&O
New York City–headquartered
For U.S. businesses that build or use AI. Protection for management, professional and employment exposures alongside existing insurance.
Issuing-carrier financial strength
A- (Excellent)
Hadron Specialty Insurance Company
AM Best · affirmed August 13th 2026
Alongside your existing insurance
Existing policies may respond. The answer depends on their insuring agreements, definitions, exclusions, limits and the circumstances of the claim. Dedicated AI liability coverage is another part of that review.
Governance, contracts and human review help manage risk. They can coexist with a need to consider how an allegation would be insured.
Read the coverage questionsDedicated AI liability coverage
Mayflower’s modules address different parts of a business. These illustrative allegations show the kinds of questions to discuss with underwriting.
AI-D&O
AI Directors and Officers Liability
Illustrative allegation
Shareholders allege that directors overstated the company’s AI capabilities or failed to oversee its use of AI.
Explore AI-D&OAI-E&O
AI Professional Liability
Illustrative allegation
A client alleges that an error in AI-assisted professional work caused a financial loss.
Explore AI-E&OAI-EPL
AI Employment Practices Liability
Illustrative allegation
An applicant alleges that an AI-assisted hiring decision was discriminatory.
Explore AI-EPLAI DIC Excess
A difference-in-conditions layer over existing D&O, EPL and E&O insurance, written to add affirmative AI coverage where those policies are silent on AI or exclude it.
How the layer worksExamples are illustrative, not Mayflower claims or promises of coverage. The issued policy determines the response. Where modules share an aggregate limit, it is one shared pool, not a separate full limit for each module. Defense costs reduce and may exhaust the available limit.
Insurance and reinsurance backing
Mayflower brings the specialist underwriting. An issuing insurance company provides the policy, supported by institutional reinsurance partners. These are distinct roles.
Managing general agent
Issuing carrier
Reinsurance placement
Each organization is named for its role in the program as announced on June 24th 2026, not as an endorsement of Mayflower. Coverage is subject to the terms of the policy as issued. For the latest Best’s Credit Rating, access www.ambest.com (opens in a new tab).
Program announcement, June 2026 (opens in a new tab)AM Best, rating affirmed August 2026 (opens in a new tab)
Why Mayflower
Mayflower brings insurance and AI experience to the same conversation: what your business does, how it governs its systems and where a liability claim could arise.
Dedicated management, professional and employment liability modules, with an AI DIC Excess option for an existing program. The wording and the facts of a claim determine the response.
Your AI inventory, oversight, testing and incident response give underwriting context for the exposure. Controls matter without making a business immune to allegations.
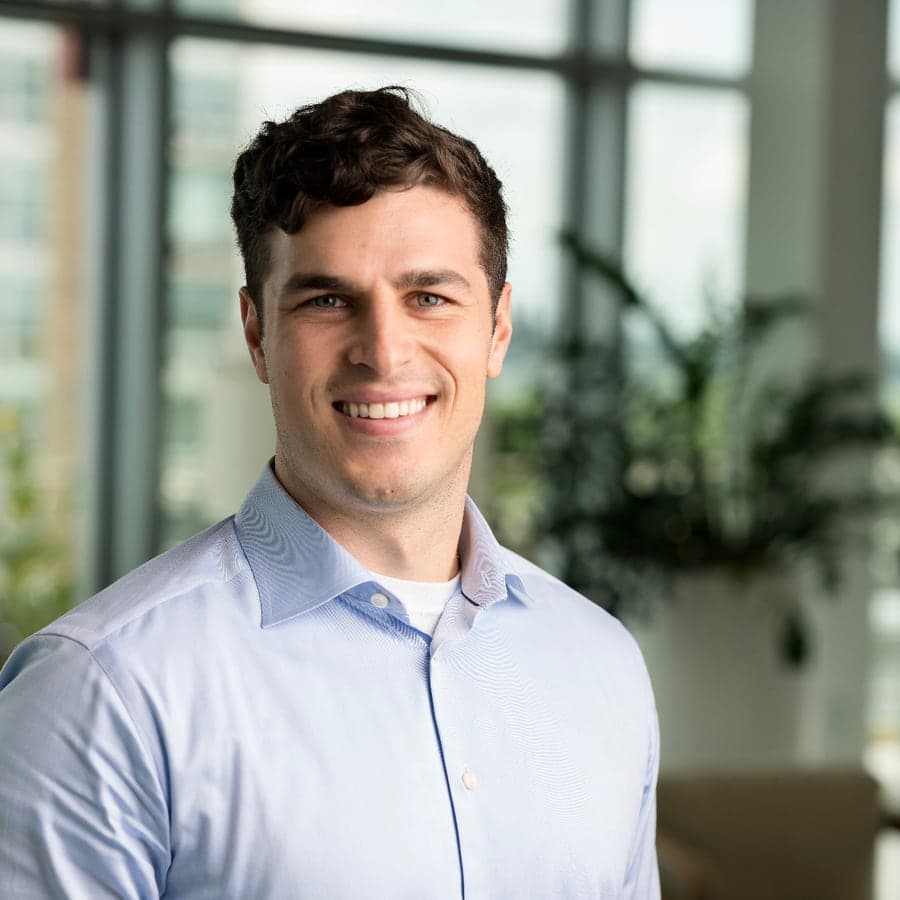
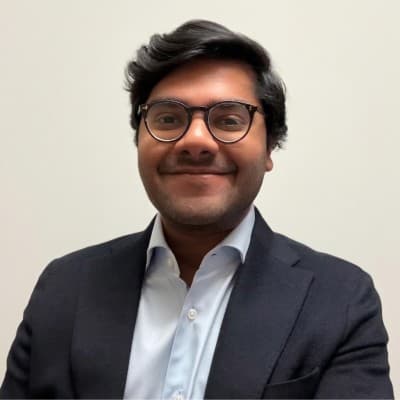
Founder and CEO Jeremy Epstein previously worked at American Family Ventures and Nationwide. Advisor Aman Raghuvanshi brings experience deploying AI and building insurance technology.
Company investors
Clocktower Ventures
Antler
Investment in Mayflower’s business is distinct from the insurance and reinsurance capacity supporting its policies.
About the company
Recognition
Selected for the FinTech Innovation Lab New York 2026 class
A 12-week program established by Accenture and the Partnership Fund for New York City.
Read about the selectionPress & interviews
Perspectives on AI liability, emerging risks and the future of specialty insurance.
Research inclusion
Coverage
Interview
The June 2026 program launch was reported by Business Insurance: Mayflower, Hadron unveil affirmative AI liability program (opens in a new tab), Intelligent Insurer: Mayflower addresses ‘new class of liability’ in Hadron partnership (opens in a new tab), AM Best News: MGA Mayflower Specialty and Hadron Launch Affirmative AI Program They Call a US First (opens in a new tab), Commercial Risk: Mayflower, Hadron unveil affirmative AI liability programme (opens in a new tab), Reinsurance News: Mayflower and Hadron launch US dedicated affirmative AI liability program (opens in a new tab) and Coverager: Mayflower and Hadron launch AI liability insurance program (opens in a new tab).
How it works
Start with a discussion or bring an application. You or your broker can explain the exposure, document your controls and review any terms with the underwriting team.
Tell us what your business builds or uses, where AI affects decisions and what you want to understand about coverage. Brokers are welcome to bring a client’s questions.
Discuss AI coverageComplete the supplemental application online, with email verification and saved progress, or use the PDF. Underwriting reviews your AI systems, governance and existing insurance.
Start an applicationConsider the coverage, exclusions, limits and retention alongside your existing program. An application is a request for underwriting review and does not bind coverage.
Underwritten on your governance
After the applicant details, the application asks about seven areas of AI risk and governance. Each one tells underwriting something about the size of the exposure or the controls that contain it.
The number of AI systems, how autonomous they are and whose decisions they affect describe the exposure underwriting assesses.
Underwriting looks at how AI is overseen, documented and approved before a system reaches production.
The data a model learns from and acts on can give rise to bias, privacy and intellectual property claims, so underwriting asks how it is controlled.
Monitoring and fallback plans show how quickly a failing system would be noticed and contained.
Underwriting assesses how the company would detect, contain and learn from an AI incident.
The laws and regulators that apply to your AI systems shape the regulatory exposure underwriting assesses.
Past claims, known circumstances and prior declinations are part of underwriting any liability policy.
The application also asks for supporting material such as board or committee minutes on AI risk oversight, bias audit results and an AI incident response plan.
Questions
These are short answers for buyers and brokers, and each topic has a fuller treatment on the coverage pages and in the guides.
More answers in the FAQTwo ways to start
Tell us how your business uses AI and what you want your insurance to address. Ready to apply? Choose the online application or the PDF.
Applications are reviewed by underwriting. Completing an application does not bind coverage.